CrestbournePrivate Wealth Begin a conversation
Independent since 1974

Wealth measured in generations, not quarters.

Crestbourne is an independent, fee-only fiduciary. We manage portfolios, estates and family offices for families who intend to still be here in fifty years.

$4.2BAssets under stewardship
1974Year the firm was founded
31Years, average client tenure
0Commissions. Ever.

The horizon we plan against — 1974 → 2044Three generations · seven market cycles

PLANNED · NOT YET LIVED
1974 · Founded 1998 · 2nd generation 2026 · Today 2044 · 3rd generation
What we do

Four disciplines, one balance sheet.

Most families arrive with an investment problem and discover it was an estate problem, or a tax problem, or a family-communication problem. We staff all four so nobody has to coordinate their own advisers.

Each discipline in full
01

Portfolio management

Globally diversified, low-turnover portfolios built around your actual liabilities — school fees, a business sale, a fifty-year endowment — not a risk questionnaire.

  • Asset allocation
  • Tax-loss harvesting
  • Concentrated-stock unwind
  • Private markets access
02

Estate & trust

Structures that survive the people who wrote them. We draft with your attorney, fund the trusts properly, and revisit them when the law or the family changes.

  • Revocable & irrevocable trusts
  • Generation-skipping planning
  • Charitable vehicles
  • Trustee services
03

Tax strategy

Tax is the largest expense most families will ever carry. We plan for it across the decade, not in the last week of December.

  • Multi-year projections
  • Gifting & exemption use
  • Business-sale structuring
  • Coordination with your CPA
04

Family office

For families whose affairs have outgrown a single adviser: consolidated reporting, bill pay, next-generation education, and a governance forum that keeps everyone speaking.

  • Consolidated reporting
  • Governance & family council
  • Next-gen financial education
  • Philanthropic administration
Our approach

We are paid to be boring.

A long horizon is not a slogan — it is a constraint we accept. It means we will decline to chase the year's best-performing asset class, and it means we will look wrong for stretches. We think that is the price of being right over thirty years.

Our portfolios turn over roughly 8% a year. We rebalance on rules, not on conviction. And we tell you, in writing, what would have to be true for us to change our minds.

Read our investment policy

Signal against noise

Illustrative · 30 years
Year 1Year 15Year 30
What the market does What we plan against
The generational band

A client relationship, drawn across three lifetimes.

This is the arc of an actual Crestbourne relationship — anonymised, and typical. The work changes at every handover. The mandate does not.

1978 — First generation

The founder

A manufacturing business, one illiquid balance sheet, and no plan beyond the next order book. We began where we always begin: a liquidity plan, and a will.

ObjectivePreserve the operating company
1998 — Second generation

The sale

The company sold. Overnight, an operating family became an investing family — a harder transition than it sounds. We built the first portfolio and the first trust.

ObjectiveConvert a business into an endowment
2019 — Third generation

The many

Four households, three countries, one shared portfolio and diverging views. We stood up a family council, wrote a constitution, and separated the money that must stay from the money that may go.

ObjectiveKeep a family talking to each other
2044 — Fourth generation

Not yet ours

Children who are not yet adults will inherit the decisions we are making this year. That is the discipline the entire firm is organised around.

ObjectiveHand over something intact
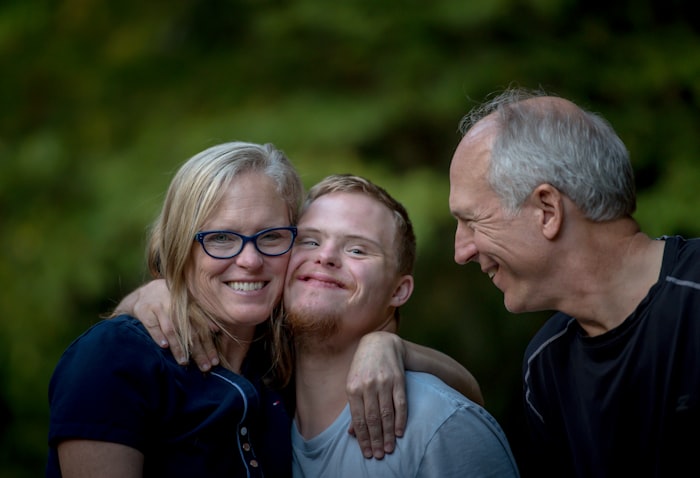
Three members of a family across two generations standing together outdoors
“My father chose Crestbourne. I kept them because they told me, plainly, when I was about to do something foolish — and because they say the same thing to my daughter now.”
Client, second generationRelationship since 1998

Fiduciary, in writing

We are legally bound to act in your interest — and we put that duty in the engagement letter, not the footnotes.

Fee-only, no commissions

One transparent fee on assets we manage. We are paid by you and by nobody else — no product, no platform, no referral.

The fee, stated plainly

0.85% to $5M · 0.65% to $20M · 0.45% thereafter. Family-office mandates are quoted as a flat annual retainer.

Independent custody

Your assets are held at a third-party custodian in your name. We can trade them. We can never withdraw them.

Crestbourne Private Wealth LLC is a registered investment adviser. Registration does not imply a level of skill or training. Investing involves risk, including the possible loss of principal; past performance does not guarantee future results.

Our people

You will know who answers the phone.

Twenty-two people serve ninety families. Every relationship is led by a partner, and no partner carries more than a dozen. When you call, you will not be routed.

Portrait of Alistair Crewe, Managing Partner at Crestbourne

Alistair Crewe

Managing Partner

CFA · Joined 1996

Portrait of Marguerite Devereux, Head of Estate & Trust at Crestbourne

Marguerite Devereux

Head of Estate & Trust

JD, LL.M. Tax · Joined 2004

Portrait of Ayo Adeyemi, Partner and Head of Family Office at Crestbourne

Ayo Adeyemi

Partner, Family Office

CPA/PFS · Joined 2011

Portrait of Theo Mensah, Chief Investment Officer at Crestbourne

Theo Mensah

Chief Investment Officer

CFA, CAIA · Joined 2008

Client work

Three problems we were actually hired for.

We do not publish client names or balances. What we can describe is the shape of the problem and what changed.

Liquidity event

A founder with 94% of her wealth in one stock, and a lock-up expiring in eleven months.

We built a staged unwind with a collar, pre-funded the tax, and moved a slice into a charitable trust before the sale — so the gift went out at a low basis rather than a high tax bill.

Engaged 2021 · ongoing

Family governance

Four siblings, one inherited portfolio, and no mechanism for disagreeing.

The money was never the problem. We separated the shared endowment from individual accounts, chaired the first three family meetings, and wrote the decision rules everyone signed.

Engaged 2017 · ongoing

Succession

A widow told she had to sell the family land within the year to cover estate tax.

She did not. A prior adviser had never funded the trust that existed on paper. We valued the estate properly, elected instalment relief, and the land stayed with the family.

Engaged 2014 · ongoing

Begin a conversation

The first meeting costs nothing and commits you to nothing.

An hour with a partner. Bring the question that has been sitting unanswered — the sale, the trust, the child who is about to inherit. We will tell you plainly whether we are the right firm, and if we are not, who is.

Minimum relationship $2,000,000 · Boston · Charleston · Zurich