CrestbournePrivate Wealth Begin a conversation

Crestbourne/Our approach

Our approach

We are paid to be boring.

A long horizon is not a slogan — it is a constraint we accept. It means we will decline to chase the year's best-performing asset class, and it means we will look wrong for stretches. We think that is the price of being right over thirty years.

What we believe

Six beliefs we would defend in front of a client.

Not a philosophy page written to sound wise. These are the positions that actually determine what ends up in your portfolio, and each one costs us something.

01

The plan comes before the portfolio

We will not propose an allocation until we know what the money is for and when it is needed. A risk questionnaire measures how you felt on the day you filled it in; a liability schedule measures what you owe the future.

This is why our first meeting asks about your children and your business rather than your appetite for volatility.
02

Cost is the only return we can guarantee

We cannot promise a market return. We can promise that a basis point not paid is a basis point kept. So we favour low-cost vehicles, keep turnover near 8% a year, and audit every underlying expense annually.

It is also why we are fee-only. A commission is a cost you cannot see.

03

Rebalancing is a rule, not a judgement

Every sleeve has a band. When it breaches, we trade — including into a falling market, which is the only time it is genuinely uncomfortable and the only time it reliably matters.

Writing the rule down in advance is how we stop ourselves from becoming market timers with better vocabulary.

04

Tax is part of the investment decision

A pre-tax return is a number for brochures. We site assets by account type, harvest losses when they are offered, and hold gains where a step-up is coming rather than trading for a marginally better fund.

The most valuable trade in a decade is often the one we declined to make.

05

We will tell you what would change our minds

Every recommendation we write includes the conditions under which we would reverse it. If we cannot state those conditions, we do not understand the position well enough to hold it on your behalf.

It also makes us accountable in a way a performance number never quite is.

06

The family is part of the mandate

Most of the damage we have watched happen over fifty years was not caused by markets. It was caused by a family that had never agreed how decisions get made, meeting a large sum of money for the first time.

So governance, education and plain conversation are part of the work, not an add-on service.

Signal against noise

What we plan against is not what the market does.

The grey line is the year-to-year experience of owning risk assets: violent, unhelpful, and impossible to predict. The bronze line is the only thing we can plan against — a long trend that only becomes visible once you stop measuring it in quarters.

Our portfolios turn over roughly 8% a year. We rebalance on rules, not on conviction. And we tell you, in writing, what would have to be true for us to change our minds.

See the four disciplines

Signal against noise

Illustrative · 30 years
Year 1Year 15Year 30
What the market does What we plan against

The rules we wrote down in advance

Rebalance triggered when any sleeve drifts past its band

±5 pts

Target portfolio turnover in a normal year

≈ 8%

Cash held against the coming year's known spending

12 months

Maximum single-security weight, ex-legacy positions

5%

Manager review — process, people, or fee change

Annual
Fee-only, and why it matters

Three ways an adviser gets paid. Only one has no second party.

"Fee-only" is a specific claim, not a tone of voice. It means every dollar of the firm's revenue comes from the clients it advises, and none of it from anyone who would like those clients to buy something.

Model one

Commission

The adviser is paid by the product provider when you buy. Advice is free at the point of delivery, which is precisely what makes it expensive.

Who pays
The product manufacturer
Structural tension
Recommending nothing pays nothing
Model two

Fee-based

A fee from you, plus commissions on some products. The word differs from "fee-only" by one syllable and by the entire question of who else is paying.

Who pays
You, and sometimes a third party
Structural tension
Disclosed in the footnotes, if at all
Model three · ours

Fee-only

One transparent fee on assets we manage, or a flat retainer for family-office mandates. No commissions, no product revenue, no platform payments, no referral fees — received or paid.

Who pays
You, and nobody else
Structural tension
Our fee rises with your assets — see below

The conflict we have not eliminated: because our fee is a percentage of assets we manage, we are paid more when your portfolio is larger. That means we have a financial interest in advising against paying off a mortgage, funding a business, or giving a large sum away — all of which reduce what we manage. We name it here because a conflict you can see is one you can hold us to. Where such a decision arises, our written recommendation states plainly what it costs the firm.

Fiduciary, in writing

We are legally bound to act in your interest — and we put that duty in the engagement letter, not the footnotes.

Independent custody

Your assets are held at a third-party custodian in your name. We can trade them. We can never withdraw them.

Written recommendations

Every material recommendation arrives in writing, with its reasoning and the conditions that would reverse it.

No proprietary products

We manufacture nothing. There is no in-house fund for us to prefer over a better one held elsewhere.

The generational band

A client relationship, drawn across three lifetimes.

This is the arc of an actual Crestbourne relationship — anonymised, and typical. The work changes at every handover. The mandate does not.

1978 — First generation

The founder

A manufacturing business, one illiquid balance sheet, and no plan beyond the next order book. We began where we always begin: a liquidity plan, and a will.

ObjectivePreserve the operating company
1998 — Second generation

The sale

The company sold. Overnight, an operating family became an investing family — a harder transition than it sounds. We built the first portfolio and the first trust.

ObjectiveConvert a business into an endowment
2019 — Third generation

The many

Four households, three countries, one shared portfolio and diverging views. We stood up a family council, wrote a constitution, and separated the money that must stay from the money that may go.

ObjectiveKeep a family talking to each other
2044 — Fourth generation

Not yet ours

Children who are not yet adults will inherit the decisions we are making this year. That is the discipline the entire firm is organised around.

ObjectiveHand over something intact
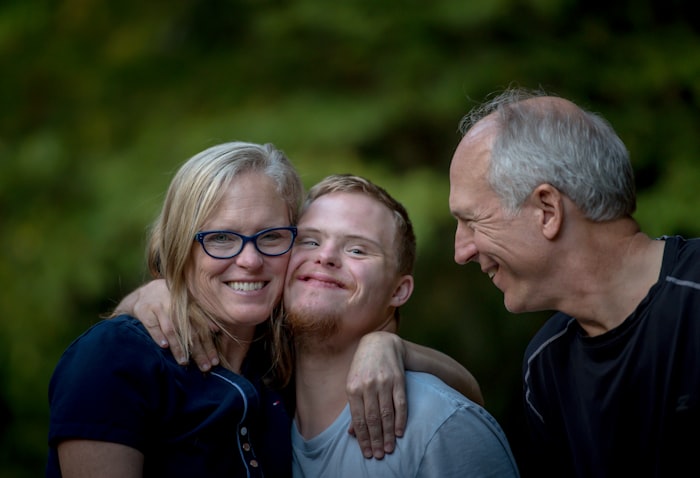
Three members of a family across two generations standing together outdoors
“My father chose Crestbourne. I kept them because they told me, plainly, when I was about to do something foolish — and because they say the same thing to my daughter now.”
Client, second generationRelationship since 1998
The handover

What actually has to happen when money changes hands.

Every relationship above passes through the same four moments. Firms that only manage portfolios meet the family at the third one, which is usually too late to help.

Ten years before

Name the intention, and write it down

Who is meant to receive what, on what condition, and what the money is for. Most families have an answer and have never said it out loud. Getting it on paper a decade early removes the argument that would otherwise happen at a funeral.

Five years before

Build the structure and actually fund it

Trusts drafted with your attorney, titled correctly, and funded. Beneficiary designations reconciled against the will. Exemption use ledgered. This is the step most commonly skipped, and it is the one that costs families land and businesses.

Three years before

Teach the people who will inherit

Adult children learn how the portfolio works, what the trusts permit, and how to read a statement — with a small supervised account of their own. Held annually, without their parents in the room, because nobody asks a naive question in front of the person who made the money.

At the handover

Change the governance, not the mandate

New decision-makers, a re-chartered family council, a re-read of every document against the new circumstances. The portfolio itself usually barely moves — which is the point of having planned against decades rather than quarters.

Begin a conversation

If this reads like the firm you want, the next step is an hour.

The first meeting costs nothing and commits you to nothing. We will tell you plainly whether we are the right firm, and if we are not, who is.

Minimum relationship $2,000,000 · Boston · Charleston · Zurich